Rising Fuel Oil Prices Trigger Asia’s Latest Economic Strain
 admin
**Asian Shipping Fuel Costs Surge Amid Supply Constraints and High Freight Rates**
Asian trade faces escalating costs as Singapore’s shipping-fuel market reaches historic highs. Disruptions to Middle Eastern and Russian export channels, sustained bunker demand, and unprecedented freight costs have driven high-sulphur fuel oil (HSFO) prices above the cost of the crude oil used to refine it. While increased production from Persian Gulf refiners and new Chinese export quotas may offer late-year relief—particularly for Very Low Sulphur Fuel Oil (VLSFO)—expensive transportation and vulnerable Russian supply lines present significant barriers to normalizing price structures.
### Shift in Pricing Dynamics
The most dramatic price adjustment has occurred in the HSFO market. Singapore’s November crack spread against Dubai crude rose above $10 per barrel in mid-October. This marks a sharp contrast to February, when the product traded at a discount of roughly $5 per barrel. This swing of over $15 per barrel demonstrates that escalating bunker costs are not merely a function of broad crude market movements, but of severe structural tightness in the fuel oil market itself.
The regional disparity remains stark. On October 7, the Singapore–Rotterdam HSFO swap spread peaked at a record $95 per tonne (approximately $15 per barrel) before moderating slightly to $88 per tonne. With European HSFO cracks trading around -$10 per barrel relative to Brent and US Gulf Coast cracks dropping below -$20 per barrel, Singapore’s substantial premium underscores an acute shortage localized in Asia.
### Supply Shortfalls from Key Regions
Supply reductions account for much of this regional premium:
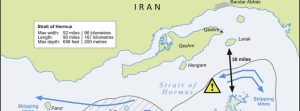
* **Middle East:** Shipments of HSFO and VLSFO to Singapore averaged 100,000 barrels per day (b/d) in 2025. These flows halted almost entirely in April and May following maritime disruptions around the Strait of Hormuz. After a brief recovery to 130,000 b/d in July, volumes plummeted to 40,000–50,000 b/d in recent months.
* **Russia:** Russian exports temporarily offset lost Middle Eastern volumes, with Singapore-bound HSFO reaching 180,000 b/d in April—well above the 2025 average range of 100,000–150,000 b/d. However, following domestic refinery disruptions stemming from Ukrainian drone strikes, Russian export volumes to Singapore dropped to 25,000 b/d by September.
The market structures for HSFO and VLSFO differ fundamentally. HSFO relies heavily on Russian and Middle Eastern exporters (including Saudi Arabia, Iran, and Iraq). VLSFO benefits from greater geographical diversity, drawing from Kuwait’s Al-Zour refinery, as well as Atlantic Basin suppliers in Brazil and Nigeria. Consequently, VLSFO buyers have access to broader sourcing options, though longer transport routes increase landed costs.
### Demand Resilience and Fleet Dynamics
Despite supply challenges, Asian demand has remained steady. Singapore recorded 4.7 million tonnes of total bunker fuel sales in September—down just 1% year-on-year, compared to a 4% average decline across July and August.
Within overall sales, consumption has increasingly favored HSFO. Year-to-date sales through September rose roughly 10% year-on-year to 17.5 million tonnes. This growth reflects the ongoing expansion of the global fleet fitted with exhaust gas cleaning systems (scrubbers), which allow vessels to burn higher-sulphur fuels legally while lowering demand for VLSFO.
This shift has created a feedback loop: supply disruptions force ships to take longer alternative routes, increasing overall fuel consumption and further straining regional fuel inventories.
### Chinese Refinery Demand
Chinese buying patterns add another dimension to regional dynamics. Chinese HSFO imports reached 3.3 million barrels in early October, rebounding from 300,000 barrels in June (though below March’s peak of 9.4 million barrels). Independent refiners in Shandong account for much of this demand, utilizing heavy fuel oils—such as Russian M100—as alternative feedstocks when crude import quotas are restricted.
However, elevated HSFO spot premiums reduce the profitability of refining fuel oil once taxes, freight, and processing costs are factored in. As margins narrow, Chinese feedstock buying is expected to cool into the final two months of the year, providing a ceiling for regional price spikes.
### Freight Rates Block Western Arbitrage
Under normal market conditions, Singapore’s premium over Western markets would open an arbitrage window, drawing surplus cargoes from Europe and the Americas. However, extreme freight rates currently prevent this balance.
* **Current Shipping Costs:** The Mediterranean-to-East Asia freight rate for a 135,000-tonne cargo stands at approximately $230 per tonne. This translates to a transport cost of roughly $36 per barrel for HSFO and $34 per barrel for VLSFO.
* **Year-over-Year Comparison:** One year prior, the same route cost $41 per tonne, representing per-barrel freight costs of just $6.50 for HSFO and $6.10 for VLSFO.
Because transportation absorbs the price differential between regions, Western arbitrage flows remain constrained. Estimated October VLSFO arrivals in Singapore from Western markets fell to 1.5–1.6 million tonnes, down from 1.6–1.8 million tonnes in September.
### Near-Term Market Outlook
Certain indicators suggest a temporary easing of market tightness:
1. **Spread Adjustments:** The Singapore M1-M2 prompt time spread for VLSFO narrowed from $38 per tonne in early October to $32 per tonne by October 23. Similarly, the HSFO M1-M2 spread moderated from $59 per tonne to $56 per tonne.
2. **Export Allocations:** China issued a 1.07-million-tonne allocation of VLSFO export quotas, allowing local suppliers to satisfy more regional bunkering demand internally.
3. **Saudi Exports:** Saudi Aramco issued export tenders for over 700,000 tonnes of HSFO for November loading from Ras Tanura and Jubail, offering immediate supply relief to the market.
4. **Seasonal Power Shifts:** Warmer weather giving way to cooler winter temperatures across the Gulf will reduce domestic oil burn for power generation in Saudi Arabia and Kuwait, releasing additional volumes for international marine markets.
Despite these factors, market relief may remain localized. If freight rates stay high, incremental supplies from refineries like Kuwait’s Al-Zour may be absorbed by closer hubs like Fujairah before reaching East Asia. Additionally, mid-October VLSFO delivery lead times in Singapore remained extended at 12–15 days, indicating that prompt supply remains tight.
Overall, VLSFO appears better positioned for market stabilization due to diverse supply routes. Conversely, HSFO remains vulnerable to ongoing Russian export losses and consistent demand from scrubber-equipped vessels. While seasonal adjustments may temper price spikes, a full normalization of Asian fuel oil prices will depend on sustained reductions in global shipping costs and the stabilization of key supply routes.