Soaring Tanker Costs Halt U.S. Crude Exports to Asia
 admin

Surging oil tanker freight rates triggered by the war with Iran have disrupted global trade routes, drastically curtailing U.S. crude shipments to Asia. Shipping costs from the U.S. Gulf Coast to China surged to a record $80 million per voyage earlier this month—a tenfold increase from pre-war averages—before settling around $60 million per supertanker.
The exorbitant transport costs have driven Asian refiners to slash orders for U.S. crude. October orders for November delivery plunged 50% month-over-month to approximately 25 million barrels. Vessel-tracking data indicates that if this buying trend persists, Asia’s U.S. crude imports for November could drop to their lowest level in seven years.
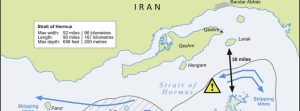
The crisis stems from severe inefficiencies in the global maritime supply chain. Efforts by Middle Eastern producers to bypass the Strait of Hormuz have tied up a significant portion of the global tanker fleet. Offshore ship-to-ship (STS) transfers in the Gulf of Oman now utilize around 80 Very Large Crude Carriers (VLCCs), with average round-trip travel times swelling from 9–10 days to 23 days. Skyrocketing freight rates in the Middle East have drawn vessels away from other international trade corridors, creating a global shortage of available tankers.
According to Valero Energy, moving a VLCC from the U.S. Gulf Coast to Asia currently costs between $30 and $35 per barrel, up from a 2025 average of roughly $5 per barrel. These elevated freight rates are forcing major shifts in regional pricing and sourcing:
* **Asia and Europe:** Buyers are prioritizing short-haul crude to minimize freight expenses. European refiners are opting for regional supplies, while Asian buyers are increasing purchases of Middle Eastern grades on a delivered basis. This shift has pushed prices for nearby crudes to record highs; Dated Brent reached a $20 per barrel premium over Brent, and Norway’s Johan Sverdrup crude hit a record $24 per