Iran’s Fuel Exports Challenge International Shipping Lanes
 admin
As the U.S. naval blockade of Iran continues to constrain crude oil exports, global petroleum trade is growing increasingly reliant on transportation expenses, regulatory limits, and maritime access. Despite these restrictions on ships near the Gulf of Oman, small quantities of refined products are still reaching foreign markets.
Maritime tracking data reveals that Iran has managed to export limited amounts of jet fuel and liquefied petroleum gas (LPG). This underscores a critical reality for energy markets: heavy restrictions on crude exports do not completely halt the movement of all petroleum products.
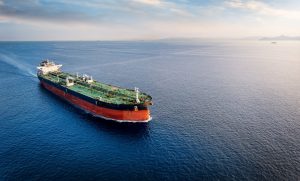
Reports from Reuters, citing maritime analysis, state that at least eight tankers holding Iranian LPG have left the Gulf of Oman since mid-July. United Against Nuclear Iran, a group tracking Iranian maritime traffic, estimates these combined LPG shipments at roughly 4.1 million barrels. Additionally, satellite data from maritime intelligence firm SynMax located a tanker delivering Iranian jet fuel to Myanmar in September.
Although these shipments are minor compared to Iran’s historical export levels and will likely not impact global supply balances, they highlight the complexities of tracking international energy shipments—especially when transfers occur at sea.
Ship-to-ship transfers are standard in legitimate energy trading for consolidating cargo, optimizing vessel capacity, and reaching ports with limited infrastructure. However, they also complicate efforts to trace cargo origins and final destinations.
The U.S. military maintains that its blockade has severely curtailed Iranian petroleum movements. U.S. Central Command stated that 135 commercial vessels were turned back during its most recent three-month enforcement cycle. U.S. officials also warned that commercial tracking data can be unreliable, as ships frequently spoof location data or operate under false identities.
These dynamics reinforce the need for global refiners and traders to thoroughly verify cargo origin documents, vessel ownership, and compliance with sanctions. Insurers and maritime operators face similar risks when assessing shipping routes and financial liability.
The broader effects on the energy market go beyond Iran. Instability around the Strait of Hormuz has pushed up tanker freight rates and complicated shipments from various Gulf producers, impacting refining margins and crude pricing. Elevated freight costs can make imported energy less competitive, particularly in regions reliant on seaborne deliveries.
For U.S. energy producers, shifting global shipping costs can alter export competitiveness and the demand for American petroleum products. Commodity traders, export terminals, and midstream companies may also see shifts in demand as buyers adapt their supply chains.
For market investors, the central question is whether these maritime constraints will cause long-term shifts in trade routes, delivered energy prices, and regional supply lines.
The trickle of refined product exports does not point to a broader recovery in Iran’s trade capacity; maritime data firm Kpler recorded zero Iranian crude exports in September. Going forward, market conditions will hinges on enforcement strength, regional security, tanker availability, and the viability of alternative shipping methods.