Elevated Prices Persist Amid Oil Supply Risks
 admin
Crude oil futures held steady on Friday, heading toward weekly gains as persistent risks to Middle Eastern shipping routes dominated market sentiment, overriding international efforts to boost market supply and lower shipping expenses.
Brent crude hovered around $106 per barrel, while West Texas Intermediate (WTI) traded near $98 per barrel. WTI was set for a notably larger weekly gain than Brent, propelled by a steep drawdown in U.S. crude stockpiles. This divergence underlines how distinct regional inventories and logistics hurdles impact the two major global benchmarks differently.
For energy market participants, the primary concern remains the physical movement of oil from extraction points to global refining hubs.
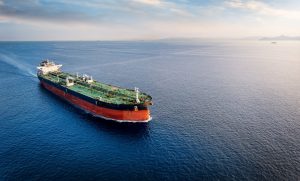
Security risks along the Strait of Hormuz continue to disrupt commercial shipping, creating delivery delays and heightening market volatility. Data from maritime tracking company Kpler indicates that daily oil shipments through the Strait averaged 11.6 million barrels during the week ending October 13—just 68% of normal operational levels prior to recent disruptions. These bottlenecks continue to buoy global oil prices despite adequate resource capacity in other regions.
At the same time, high freight rates continue to inflate the final delivered costs for refiners and global importers.
In response, several international policy interventions are underway to stabilize the market:
* The International Energy Agency (IEA) is expediting the release of remaining emergency reserves pledged earlier this year, which includes over 20 million barrels of diesel fuel.
* U.S. officials are evaluating temporary sanction relief for select oil tankers to expand available shipping capacity and curb rising transport fees.
* The U.S. has also temporarily eased specific restrictions on Russian diesel exports.
While these policy measures aim to improve global liquidity and product availability, market stability ultimately hinges on effective delivery timelines, open transit routes, and regional maritime security.
**Sector Impact:**
* **Exploration & Production (E&P):** Higher crude prices bolster cash flow and capital allocation for U.S. oil producers. However, operators face offsetting pressure from elevated service costs and potential downside risks should logistics normalize.
* **Midstream & Logistics:** Pipeline and terminal operators may see shifting flow patterns as global buyers reconfigure supply lines to bypass constrained routes.
* **Refining:** Refiners face margin compression due to higher feedstocks, unless price gains for end-products like diesel and gasoline outpace raw material costs.
For market investors, distinguishing between structural supply deficits and localized transit bottlenecks is key to predicting price longevity. While emergency reserve releases offer short-term liquidity, they do not create long-term production growth or eliminate shipping route risks.
Key factors to monitor in the coming weeks include domestic inventory reports, tanker rates, real-time flows through the Strait of Hormuz, and the execution pace of strategic stock releases. Until transit routes stabilize, energy markets are likely to remain highly reactive to geopolitical headlines.
*Disclaimer: This content is provided strictly for informational purposes and does not constitute financial, legal, or investment advice. The insights contained herein reflect market conditions at the time of writing and are subject to change without notice.*