Oil’s $110 Surge Highlights Refinery Costs and Producer Cash Flow
 admin

(Oil & Gas 360) – Worldwide crude benchmarks surged toward $110 per barrel on Friday, touching multi-month highs as escalating geopolitical friction in the Middle East and ongoing strikes on Russian energy assets intensified supply security worries.
Brent crude pushed to $109.86 per barrel before settling, and West Texas Intermediate (WTI) finished at $101.41. The price spike highlights widespread anxiety regarding global export stability and the safety of critical marine transit routes.
The market shift yields contrasting financial consequences across energy segments, notably impacting upstream operators, refining margins, and logistics networks.
Elevated commodity prices typically bolster top-line revenues and free cash flow for exploration and production firms. Upstream operators maintaining low lifting costs, robust output, and unhedged production volumes stand to gain the most from this upward momentum.
Even so, stronger crude realizations do not immediately trigger expanded capital expenditures. Management teams remain cautious, weighing market longevity before allocating capital to new drilling operations, asset purchases, or infrastructure builds.
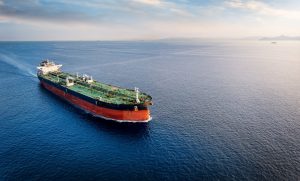
A primary driver of the latest advance is rising risk along the Strait of Hormuz, where persistent threats against maritime traffic hinder transit from key Middle Eastern export hubs.
In a related event, Saudi defense forces intercepted a ballistic missile aimed at the Red Sea port city of Yanbu, with official sources confirming no operational disruption or facility damage occurred.
Concurrently, drone strikes targeting Russian refineries have sparked fresh concerns over domestic processing volumes and the stability of downstream fuel exports.
In response to supply tightness, global policymakers are deploying counter-measures, such as tapping strategic crude reserves and easing trade constraints on select Russian middle distillate exports.
Conversely, downstream refiners face margin compression due to surging feedstock expenses. Operational profitability hinges on whether end-product prices for diesel, jet fuel, and gasoline rise fast enough to absorb the cost of crude.
Facilities with strong operational reliability and access to discounted crude slates are best equipped to navigate the current margin environment.
Logistics providers and marine terminal operators are also adapting as global traders alter shipping routes and crude sourcing strategies.
While elevated oil prices stimulate upstream activity, surging tanker rates and marine war-risk insurance premiums threaten to erode the netbacks of long-haul crude shipments.
From an investment perspective, the longevity of these price levels holds greater significance than short-term price spikes.
If sustained, higher crude realizations will accelerate balance sheet deleveraging, fund share repurchases and dividends, and enhance the net present value of prospective field developments.
On the other hand, any swift resolution to maritime security threats or easing of transit bottlenecks could quickly erase the risk premium currently priced into futures contracts.
Key variables determining market direction include daily transit volumes through the Strait of Hormuz, Russian downstream utilization rates, U.S. commercial inventory trends, global freight indices, and crack spreads.
Crude’s push toward $110 emphasizes the necessity of assessing energy exposure holistically, as rising prices generate distinct advantages and operational risks across different industry sectors.