Modest Drop in Tanker Rates Provides Minimal Relief to Global Oil Market
 admin
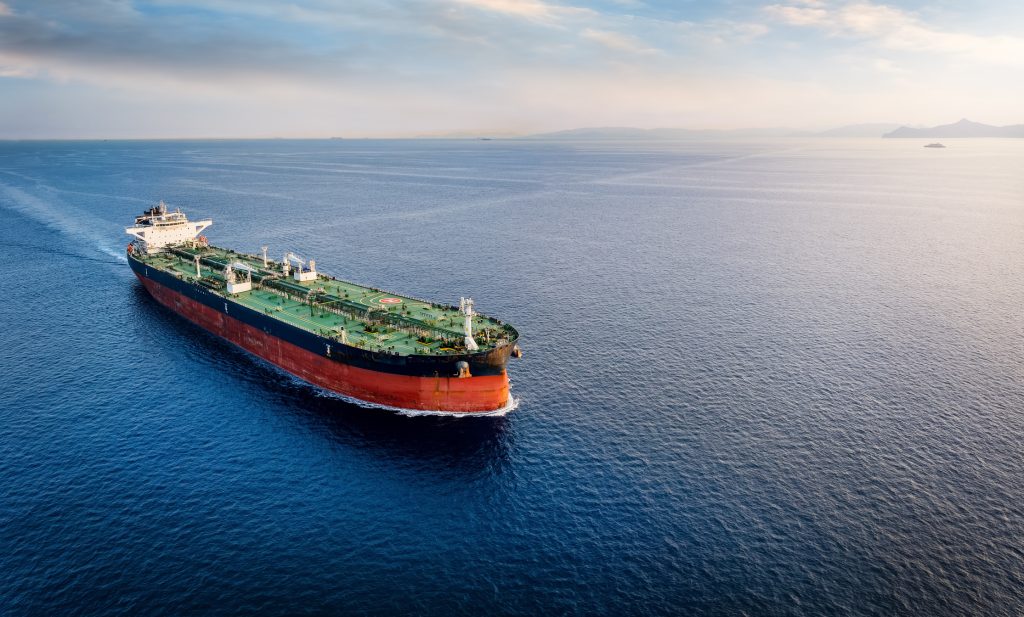

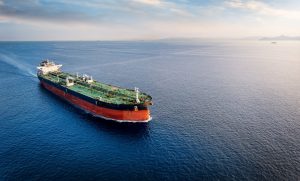
(Oil & Gas 360) – Worldwide crude oil shipping rates retreated from historic highs this week, giving global refiners and exporters a temporary reprieve while underscoring how ongoing maritime disruptions continue to reshape energy economics.
On the Baltic Exchange’s Worldscale index, benchmark pricing for Very Large Crude Carriers (VLCCs) moving crude from the Gulf of Oman to Chinese ports dropped to roughly 776, down from 841 seven days earlier.
The rate pull-back stems from cooling vessel demand along the route following new strikes against commercial shipping in the Middle East. Meanwhile, preliminary U.S. government talks regarding the potential easing of sanctions on select oil tankers helped curb bullish market sentiment.
Even with this dip, transit fees remain far above historical norms, complicating purchasing logistics and altering the price competitiveness of global oil grades.
As a result, the interplay between spot crude prices and ocean freight rates is playing a critical role in global energy trade dynamics.
Refineries determine the viability of crude purchases based on delivered costs, factoring in shipping fees, marine insurance, and port tariffs. Consequently, cheap crude at a load port can lose its competitive edge if ocean freight rates spike.
American energy exporters face significant headwinds when trying to place barrels into Asian refining hubs.
Spot charter quotes to transport a standard 2-million-barrel cargo of U.S. crude to China recently reached nearly $80 million—translating to a freight overhead of roughly $40 per barrel.
Faced with these inflated transport margins, buyers in Asia are shifting to closer supply sources, lower-cost crude grades, or shorter transit routes to safeguard refining margins.
Should freight rates sustain a downward trend, the profit margins for U.S. crude exports—particularly shipments leaving Gulf Coast terminals bound for Asia—could see marked improvement.
Nonetheless, rate relief on a single trade corridor does not guarantee a broad decline across the wider tanker market.
Tensions with Iran have heavily impacted traffic through the Strait of Hormuz, forcing a surge in mid-ocean ship-to-ship transfers. These complex operations require multiple vessels and extend voyage times, effectively tying up available fleet capacity.
Escalating security concerns and elevated insurance premiums also continue to constrain global vessel movements.
A potential policy shift by Washington to permit sanctioned vessels to carry non-sanctioned oil could bring much-needed tonnage back to the market, though official regulatory updates have yet to be enacted.
For shipowners, softening charter rates threaten to compress revenues following a long stretch of record-high earnings.
Conversely, refiners and energy traders stand to benefit from lower transport costs, provided regional supply trends, product crack spreads, and crude benchmarks remain favorable.
Midstream companies and export terminal operations are monitoring these shifting freight dynamics closely as international buyers re-evaluate cargo logistics.
For energy market investors, shipping rates have evolved into a vital metric for gauging global supply chain efficiency and arbitrage opportunities.
Declining transportation costs facilitate smoother flows of existing supply without necessitating increases in upstream production.
Going forward, key market drivers include global vessel availability, spot rates across primary shipping lanes, war-risk insurance premiums, and U.S. sanction policy developments.
Until geopolitical security stabilizes across vital sea lanes, tanker transport fees will remain a central determinant of crude valuation, refinery spreads, and global petroleum flows.
Disclaimer
This informational, opinion, and insights article is provided for informational purposes only and does not constitute investment, legal, or financial advice. The views expressed are based on publicly available information and market conditions at the time of publication and are subject to change without notice.