G7 Oil Stock Release Offers Only Temporary Relief to Fractured Fuel Market
 admin
**G7 Oil Stockpile Release Offers Only Temporary Relief to Fragile Fuel Market**
Crude oil prices and middle distillate cracks declined late last week following an announcement by the G7 nations and their partners to release 100 million barrels of oil reserves over a four-month period. This coordinated effort features a heavily front-loaded distribution of diesel within the first 20 days.
The market responded positively to the news, pushing oil prices downward. In the United States, gasoline and diesel prices fell alongside the domestic crude benchmark, WTI, which slipped to approximately $90 per barrel. Additionally, several U.S. states have implemented motor fuel tax holidays through the end of the year to further ease consumer costs.
While the immediate price drop indicates that market participants are focusing on the short-term influx of diesel, analysts warn that this release is merely a temporary fix for a structurally tight market.
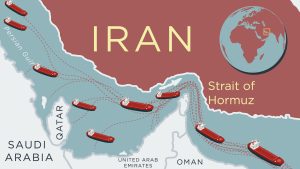
Once the initial impact of the release fades, concerns regarding depleted emergency reserves are expected to resurface. Analysts point out that drawing down already low stockpiles without a reliable source of replenishment leaves the global fuel market highly vulnerable to future supply shocks. Furthermore, the current price relief will likely be short-lived unless normal fuel shipments resume through the critical Strait of Hormuz.
For U.S. President Donald Trump, the drop in fuel prices serves as a timely political victory just ahead of the November mid-term elections. However, while governments focus on immediate relief at the pump, financial markets operate on a longer horizon. If supply disruptions from Russia, China, and the Middle East persist, the global fuel deficit could easily extend well into 2027.
Ole Hansen, Head of Commodity Strategy at Saxo Bank, noted that while stockpile releases can offer temporary relief during peak demand periods, long-term stabilization requires restoring refinery output and trade flows. According to Hansen, a sustained decline in Brent crude prices depends on improved crude supply, a recovery in product exports, and a reduction in the political and financial risks currently impacting global shipping.
Refineries across Europe, Asia, and the United States are currently unable to compensate for production deficits in Russia and the Middle East. Meanwhile, China has once again halted fuel exports to prioritize its domestic market. Although Chinese fuel exports surged between July and September after Beijing eased restrictions, new limits in October barred fuel exports beyond Hong Kong and Macau ahead of the Golden Week holiday. It remains uncertain whether China will resume export authorizations after the holiday concludes.
In Russia, the government has extended its ban on exports of diesel, marine fuel, and gasoil through October 31. This extension prolongs the global market’s struggle to operate without Russian diesel shipments, a situation exacerbated by ongoing Ukrainian drone strikes on Russian refineries that have severely damaged domestic refining capacity.
Additionally, fuel supplies from the Middle East remain limited, despite official claims that shipping volumes through the Strait of Hormuz have returned to or exceeded pre-conflict levels.
Ultimately, until the fundamental supply constraints of the global fuel market are resolved, emergency stockpile releases will remain a short-term band-aid that risks leaving global inventories even more depleted and vulnerable in the future.