Russian Western Oil Exports Set to Drop in November as Refineries Recover
 admin
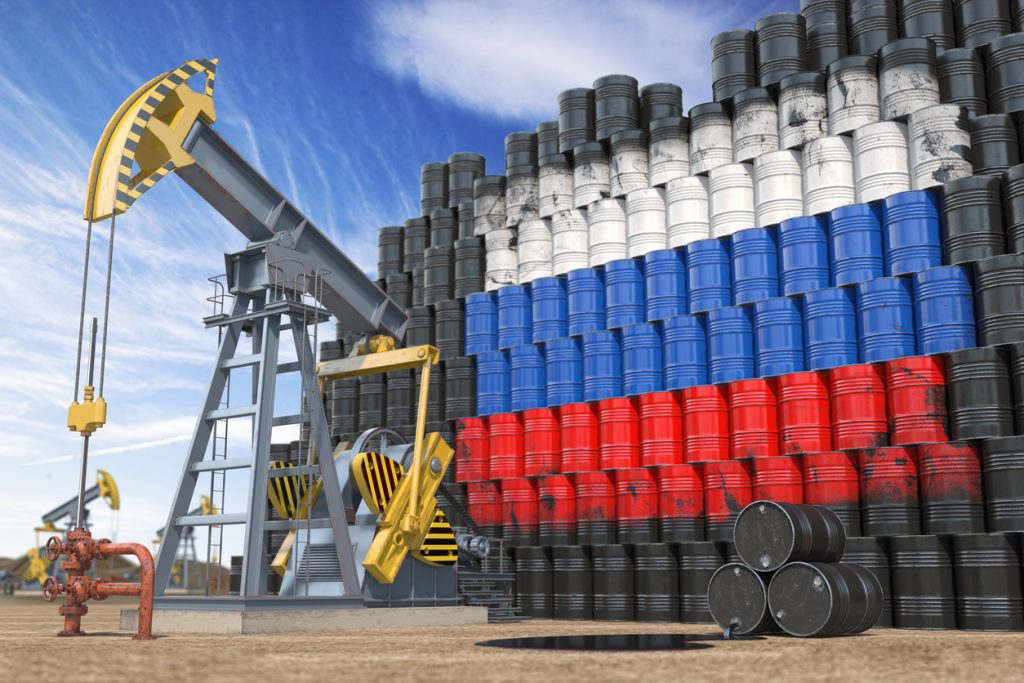
Seaborne crude exports from Russia’s western terminals are projected to fall in November as domestic refineries ramp up operations to boost diesel output. This operational pivot is expected to trim crude shipments while adding fuel supply to a global market navigating Middle Eastern disruptions.
According to market sources, November shipments from Russia’s Baltic and Black Sea ports—which include Kazakh volumes routed through Russian networks—could drop by 100,000 to 200,000 barrels per day from October levels.
The drop in crude exports coincides with the conclusion of seasonal refinery maintenance and follows an October 9 diplomatic arrangement between the U.S. and Russia. Under this agreement, Washington temporarily loosened restrictions on Russian fuel exports, and Moscow eased its internal diesel export limits. The coordinated effort aims to stabilize global diesel availability amid ongoing supply shocks linked to conflict involving Iran.
Data indicates Russian refinery output is already rebounding. Daily diesel production dipped to roughly 160,000 metric tons in early October—down from 175,000 metric tons in September—before climbing toward 180,000 metric tons as expanded export quotas took effect.
While higher refining rates release more finished products like diesel into global trade, they simultaneously reduce the volume of raw crude available for direct export. However, Russia’s capacity to sustain higher run rates faces significant headwinds:
* **Infrastructure Attacks:** Ongoing Ukrainian drone strikes on refineries and transit hubs have repeatedly disrupted operations throughout 2026.
* **Production Declines:** Recent OPEC data points to contracting Russian crude output, following a official forecast revision in September that lowered Russia’s 2026 production outlook to a 17-year low.
* **Logistical Bottlenecks:** Black Sea loading delays at Novorossiysk have stretched near three weeks due to heightened security protocols and operational hazards.
* **Seasonal Constraints:** Deteriorating Arctic weather in November is set to restrict navigation along the Northern Sea Route, curbing crude flows to Asian buyers.
For global energy markets, these developments create offsetting pressures. Lower crude exports threaten to tighten raw material supplies for global refiners, particularly in Asia. Conversely, an influx of Russian diesel could alleviate global fuel shortages, putting downside pressure on refining margins and regional product pricing. Market participants will be tracking November loading manifests, refinery run rates, and maritime traffic to assess the net impact on global petroleum balances.