Ovintiv Acquires Logan Energy for $890 Million to Expand Montney Oil Footprint
 admin
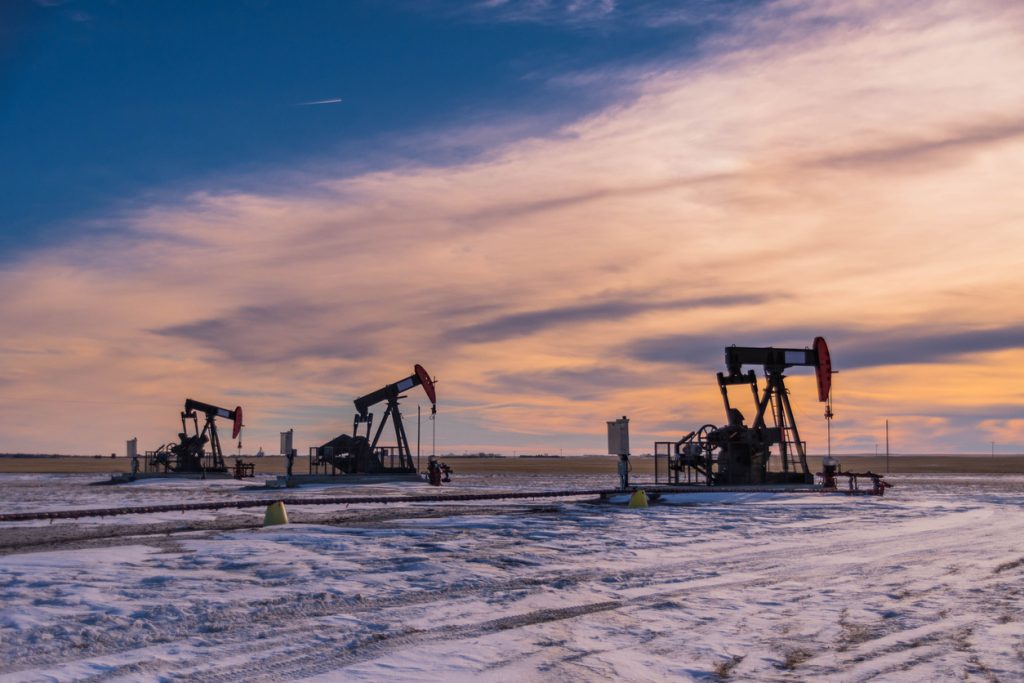

(Oil & Gas 360) – In a deal that further expands its footprint in western Canada’s oil-rich Montney formation, Ovintiv on Monday revealed a definitive agreement to purchase Canadian energy producer Logan Energy Corp. The all-cash transaction carries an enterprise value of roughly $890 million (CA$1.26 billion), inclusive of anticipated net debt.
Logan investors are set to obtain CA$1.40 (around $0.99) for each share held. Pending approval from shareholders, regulatory bodies, and the courts, the transaction is slated to finalize early in Q1 2027.
The deal delivers roughly 266,000 net acres and daily output of 20,000 barrels of oil equivalent (boe/d). This production mix consists of 7,000 barrels per day of condensate and crude, 70 million cubic feet per day of natural gas, and 1,000 barrels per day of additional NGLs.
Post-closing, Ovintiv’s key Montney position will expand to nearly 720,000 net acres, consolidating its presence across a premier North American shale play.
Included in the purchase are about 420 net drilling sites (standardized to 10,000-foot laterals), with Ovintiv designating 220 of these as top-tier inventory.
These top-tier locations are modeled to deliver internal rates of return above 35% based on benchmark pricing of $55/bbl West Texas Intermediate crude and $2.75/MMBtu natural gas.
Situated primarily in the Pouce Coupe and Simonette regions, the acreage borders Ovintiv’s existing leasehold, offering immediate operational and infrastructural synergies.
In addition to acreage, the transaction includes two recently built oil processing plants capable of handling a combined 24,000 barrels daily, along with equity stakes in two gas processing facilities.
Ovintiv anticipates driving annual cost synergies of roughly $60 million by streamlining G&A, optimizing field operations, and lowering drilling expenses.
Per-well capital outlays on the new acreage are expected to drop by more than $2 million.
This transaction highlights an ongoing trend of consolidation across the Canadian Montney, where operators are combining assets to build scale, lengthen drilling queues, and maximize capital discipline.
For market watchers, the overall success of the buyout will hinge on Ovintiv’s ability to smoothly blend the properties and capture its target savings without eroding development returns.
Corporate forecasts indicate the deal will be 5% accretive to 2027 non-GAAP cash flow per share and 3% accretive to non-GAAP free cash flow per share.
Ovintiv intends to fund the buyout using cash reserves, commercial paper issuances, and draws on its credit facility.
Management projects post-transaction net debt will stay under $4 billion, while upholding its strategy to distribute at least 60% of 2026 non-GAAP free cash flow to equity holders.
Under the transaction terms, Logan assets situated outside the Duvernay and Montney plays will be spun off into a standalone entity owned by Logan’s existing shareholders.
Moving forward, the market will keep a close eye on the regulatory review process, integration expenses, asset yield, and the delivery of promised synergies.
Ultimately, this acquisition enlarges Ovintiv’s inventory while underlining the critical role of scale and efficiency in modern North American resource development.
Disclaimer
This informational, opinion, and insights article is provided for informational purposes only and does not constitute investment, legal, or financial advice. The views expressed are based on publicly available information and market conditions at the time of publication and are subject to change without notice.