
Forecasted 13% Production Surge Accelerates Alaska’s Oil Comeback
 admin
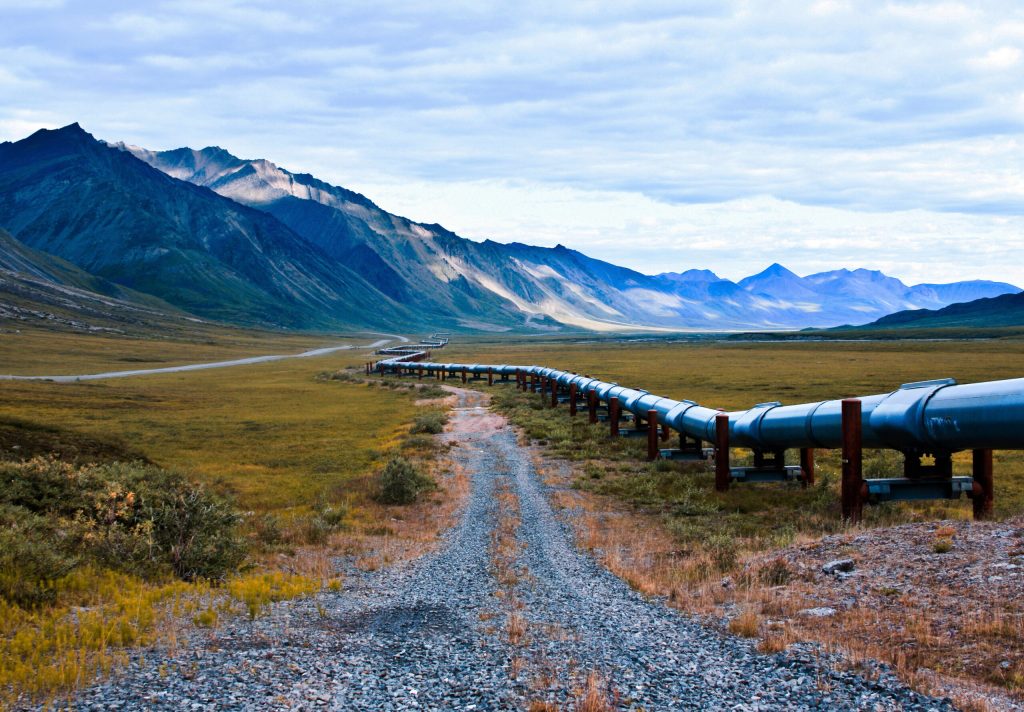

(Oil & Gas 360) – Data from the U.S. Energy Information Administration (EIA) indicates that Alaska’s crude oil output is set to jump 13% in 2027, marking a decade-plus high. Fresh developments across the North Slope are projected to inject substantial new supply, reversing decades of downward trends in a state rich with conventional petroleum reserves.
The EIA’s November Short-Term Energy Outlook estimates that Alaska will produce an average of 505,000 barrels per day (bpd) in 2027—a surge of roughly 60,000 bpd over prior levels, marking the highest volume since 2014. Operational enhancements and incoming projects are also slated to boost production by 23,000 bpd (6%) in 2026.
This upward momentum stems primarily from two major North Slope ventures: ConocoPhillips’ Nuna field and the Pikka Phase 1 project, operated by Santos alongside Repsol. Both assets benefit from existing regional infrastructure connecting directly into the Trans-Alaska Pipeline System (TAPS).
Nuna came online in December 2024 under ConocoPhillips and maintained an average output of around 10,000 bpd through 2026. The asset is engineered to hit a maximum rate of 20,000 bpd, serving to buffer output losses from surrounding legacy fields.
Santos’s Pikka Phase 1 is positioned to drive the majority of the incoming volume. After achieving first oil in May 2026, the facility registered 38,000 bpd by September, with projections showing output ramping up toward an 80,000 bpd peak throughout the 2026–2027 winter season. Pikka stands out as one of the most prominent conventional crude undertakings in the region in recent history.
During the third quarter of 2026, state output posted a 4% year-over-year gain—the first Q3 increase recorded in over 40 years. Meeting the EIA’s targets would signal a notable pivot from the structural decline that followed Alaska’s historical peak of nearly 2 million bpd in the late 1980s.
Higher volumes also offer structural relief for TAPS, which has contended with operational challenges from low throughput. Increased flow improves pipeline efficiency and spreads fixed operational expenditures across larger transport volumes, though overall asset margins remain tied to market pricing and transport logistics.
For market participants, Alaska’s trend underlines the value of major conventional projects linked to established midstream networks. Key players including ConocoPhillips, Santos, and Repsol are positioned to gain from the added volume, provided project returns effectively navigate volatility in crude pricing, transport fees, and field maintenance costs.
Across the entire United States, the EIA anticipates total crude output to hit an all-time peak of 14.3 million bpd in 2027. While Alaska represents a minor share relative to Lower 48 tight oil plays, its trajectory illustrates how targeted capital allocation can prolong the life of legacy basins.
Moving forward, the primary focus will center on whether Alaska can maintain this growth trajectory post-Nuna and Pikka by drawing continuous capital to future North Slope assets.
About Oil & Gas 360
Oil & Gas 360 is an energy-focused news and market intelligence platform delivering analysis, industry developments, and capital markets coverage across the global oil and gas sector. The publication provides timely insight for executives, investors, and energy professionals.
Disclaimer
This informational, opinion, and insights article is provided for informational purposes only and does not constitute investment, legal, or financial advice. The views expressed are based on publicly available information and market conditions at the time of publication and are subject to change without notice.




