Rising Tank
 admin
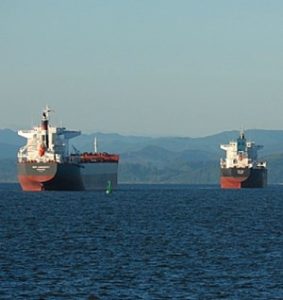
Global crude oil freight rates have surged roughly sevenfold over the past year, placing fresh strain on energy markets even as Middle Eastern suppliers resume exports interrupted by the conflict with Iran.
According to an October 20 report from Goldman Sachs, average worldwide crude shipping costs have jumped to over $20 per barrel, up from around $3 last year. On specific Middle Eastern transit corridors, freight fees have surpassed $35 per barrel.
The financial institution cautioned that prolonged high transport expenses could drive Brent crude above its baseline projections of $90 per barrel by the end of 2026 and an $80 average throughout 2027.
This cost spike stems from shifts in maritime logistics following strikes on merchant ships and operational disruptions near the Strait of Hormuz. Goldman Sachs noted that increased war-risk insurance surcharges, elevated vessel fuel prices, and ship-to-ship transfer requirements account for most of the global freight inflation.
While these workaround logistics have enabled crude exports to resume from the Persian Gulf, they demand extra tankers, additional cargo handling, and extended transit times. The bank calculates that roughly one-sixth of the tankers active in the Persian Gulf and Gulf of Oman participate in ship-to-ship transfers daily.
The resulting squeeze on tanker availability creates ripple effects worldwide. Elevated vessel demand and extended transit routes raise freight costs across other global shipping lanes, altering the market competitiveness of crude sourced from various international regions.
For refining operations, freight charges represent a major portion of overall crude procurement expenses. Consequently, high shipping rates can prevent refiners from benefiting from lower delivered crude prices, even when baseline benchmark oil prices drop.
The overall financial burden on refiners varies based on plant location, specific crude grade demands, logistics contracts, and their ability to pass these costs along to buyers of finished petroleum products. Extended shipping constraints could prompt refiners to source crude from nearby regional suppliers, potentially altering traditional trade patterns and regional price spreads.
For American energy producers, these structural market shifts could alter foreign demand and realized crude values, particularly for firms focused on international sales. Meanwhile, domestic refiners face varying market impacts depending on their access to inland pipelines, Gulf Coast import terminals, and global export markets.
The logistical bottleneck is also impacting middle distillates and marine fuels. Goldman Sachs noted that a sluggish rebound in Middle Eastern refined product shipments could prolong tight bunker fuel supplies, imposing further cost pressures on commercial maritime operators.
For energy market investors, separating production volume